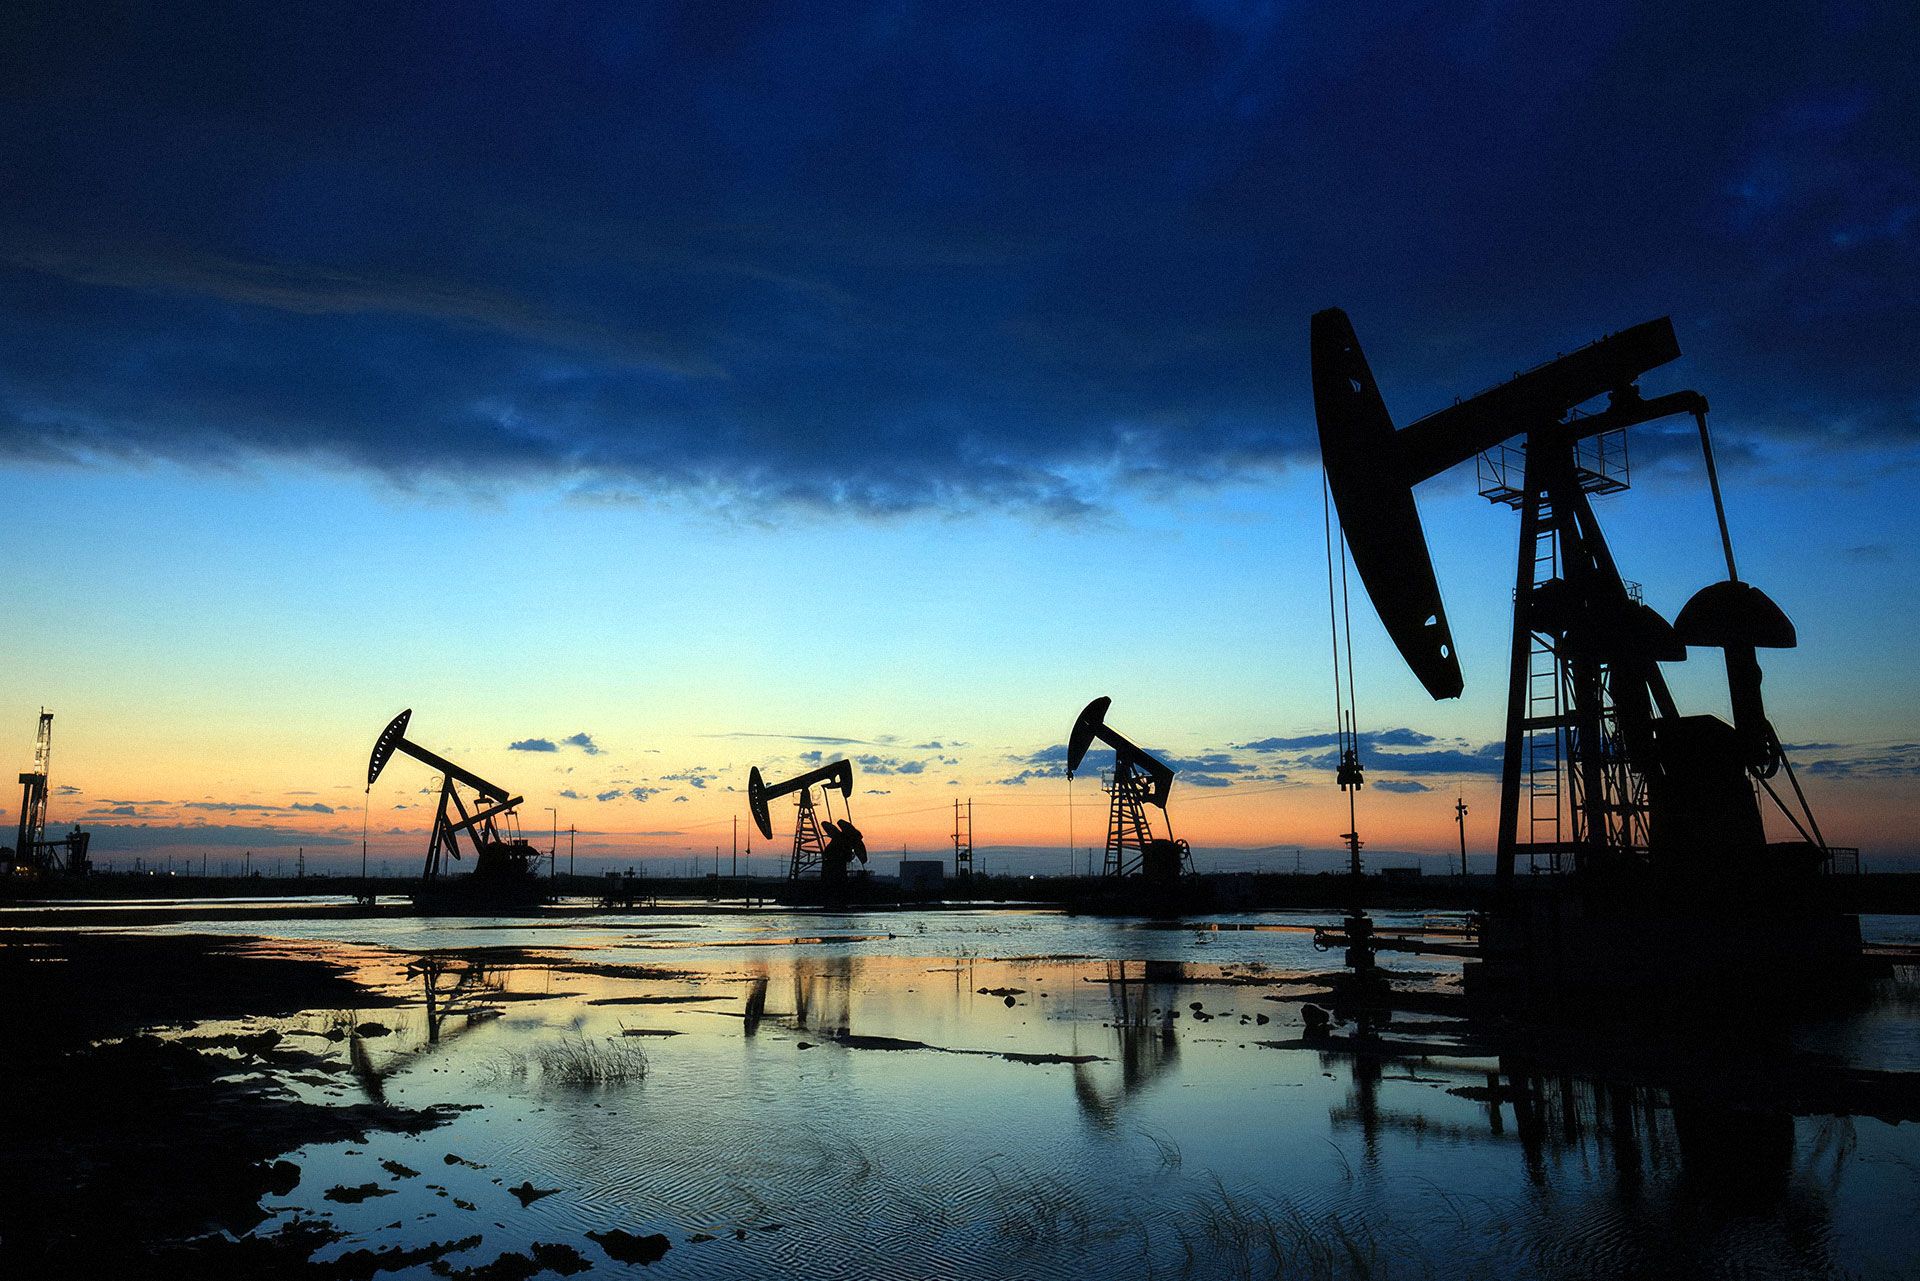
On Monday, May 12, oil futures reacted positively to news of a tariff agreement between the US and China. However, this news did not reverse the downward trend. Meanwhile, Russian oil is trading below the budgeted cut-off price and even below the cap set by Western sanctions. And this is worrying.
Brent oil prices for April 2025 stood at $68 per barrel, $5 lower than in March, and it is expected that the average annual price will be $66 per barrel. This was driven both by the OPEC+ decision to increase production by 2.2 million barrels per day by November 2025 and by slowing demand, especially in China, where consumption has declined. Russian Urals oil, which is usually cheaper than Brent, is trading at $51-56 per barrel, below the budget mark of $70.
As a result, according to the Ministry of Finance, oil and gas revenues fell by 12% in April, which economist Sergey Aleksashenko notes is not yet critical, but there is, as they say, a nuance. Considering the specifics of the Russian method of calculating VAT and export duty, as well as the timing of tax payments (quarterly),
already in May, oil and gas revenues are expected to be roughly half of April’s – 540-560 billion rubles versus 1082 billion, or about 30% less than the average in November-February.
And this is without taking into account the sanctions adopted by the UK and planned by the EU on “shadow fleet” tankers secretly transporting Russian oil at prices above the $60/barrel cap – 37% of such vessels are already sanctioned, and freight costs and risk discounts reduce the price of Russian oil to 15-20% below Brent. Moreover, tanker sanctions create risks of delivery delays, and while Russian oil exports in April amounted to 3.26 million barrels per day, mainly to India and China, a decline in export volumes can be expected in May-June.
However, the fall of Urals below the $60/barrel cap automatically opens the door for Russian oil to respectable “white” tanker shipments. As a result, in April, oil shipment volumes through ports increased to December last year’s levels (448 thousand tons per day), when large-scale US sanctions, including secondary sanctions, had not yet been introduced. However, the 17th EU sanctions package is still in progress, and it is possible that the price cap on Russian oil will be lowered – for example, to $50/barrel – such a possibility is embedded in the sanctions mechanism.
It is not surprising that the Ministry of Finance increased the planned budget deficit more than threefold, from about 1.2 trillion rubles to almost 3.8 trillion rubles. According to Reuters calculations, new UK (up to 100 tankers) and EU (149 tankers) “tanker” sanctions limit exports, which, combined with price declines, could reduce revenues by $200 billion annually if prices drop $10 per barrel, creating a budget deficit of 3.8 trillion rubles, confirming the Ministry of Finance’s adjustments.
However, the greatest danger to Russian oil is not sanctions but Kazakhstan.
The fact is that Kazakhstan, which accounts for 2% of global oil production, is one of the most “egregious” violators of the OPEC+ agreement. This naturally causes dissatisfaction among other cartel members, especially its leader, Saudi Arabia. And at the end of April, shortly before the next OPEC+ meeting, Kazakh authorities refused to cut production. “We will try to adjust our actions. If our partners... are not satisfied with the adjustment of our actions, we will again act in accordance with national interests with all the ensuing consequences,” said the country’s Energy Minister Erlan Akkenzhanov in an interview with Reuters.
There is an explanation for this behavior: production in the country is controlled by foreign companies. Chevron, Exxon, Shell, Eni, and Total effectively control the country’s three largest fields – Tengiz, Karachaganak, and Kashagan. Not only can the government have little influence on them, but it also has no reason to do so, since the fall in oil prices is a headache for the producing companies, while the budget will still receive what is due under investment agreements.
As a result of Kazakhstan’s stance, OPEC+ logically decided at the May meeting to maximize production increasing it by 411 thousand barrels per day. After this, further price declines were inevitable. Experts began discussing how far prices might fall if OPEC, especially Saudi Arabia, decides to stop supporting prices with quotas and resorts to dumping.
However, senior researcher at the Berlin Carnegie Center for Russia and Eurasia Sergey Vakulenko notes that compared to the 1980s, when the Saudis doubled oil supply and pushed prices down to $10/barrel, today Saudi Arabia has far fewer idle capacities, and a drop below $45/barrel would hurt the country’s own budget. However, $45/barrel is already a critical point for US shale oil and new projects of global oil giants in Guyana, as their production costs are around $40-45/barrel.
But for the Russian budget, $45/barrel is already very dangerous.
At $45 for Brent, Russian oil will cost around $35/barrel. Adjusted for dollar inflation, that’s about $12 in 1985. That was when the Saudis first crashed oil prices – and the USSR managed to hold out only five more years after that.
Besides Saudi Arabia’s dissatisfaction with its partners, there is also an objective decline in oil demand. Primarily from China, where consumption fell by 270 thousand barrels per day in Q3 2024 compared to the same period the previous year. Overall global oil demand growth in 2025 is forecast at 730 thousand barrels per day, lower than previous expectations.
Of course, the Russian economy is much better prepared for an oil shock than the Soviet one – not only because of its market nature but also because the Russian authorities are trained by previous crises. However, the population and, most importantly, the elites are accustomed to a completely different standard of living. How they will react to their wealth falling by half or two to three times is a question that can only be answered through experience. The Kremlin clearly does not want to test this.
The story with Prigozhin’s mutiny showed that security forces are good only for suppressing citizens with placards. But if citizens currently fighting on the front line come to the Kremlin asking why their payments are being delayed, anything could happen. Also, business elites, while obediently funding the government’s military fervor, might stop being so compliant when it comes to their own survival.